Overdraft Facility vs Term Loan: Choosing the Right Borrowing Option
Choosing between an overdraft facility and a term loan depends on how much money you need, how long you need it, and how predictable your repayment capacity is. Both are common borrowing options offered by banks and financial institutions, but they work differently. An overdraft facility generally provides flexible access to funds up to an approved limit, while a term loan provides a fixed amount that is repaid over a predetermined period. Understanding the difference between an overdraft facility and a term loan can help borrowers select financing that matches their cash-flow requirements and repayment plans.
Multiple Reasons to Choose Between an Overdraft and a Term Loan
There are numerous reasons to choose between an overdraft and a term loan which imply the need of the hour.
1] Advantage of Overdraft:
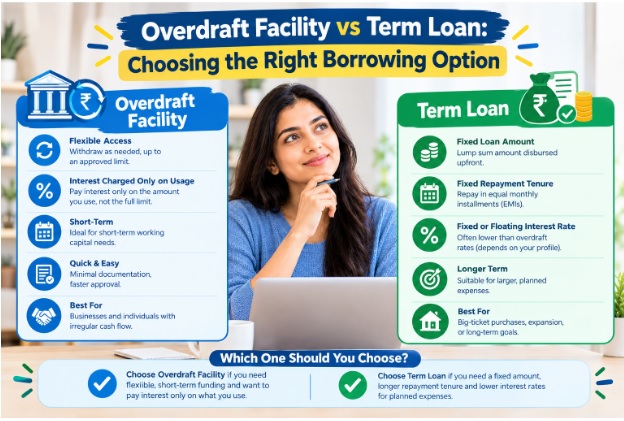
An overdraft facility can be useful when a borrower needs funds occasionally rather than receiving the entire loan amount at once. Under this arrangement, the lender approves a borrowing limit, and the borrower can withdraw money as required within that limit. Interest is generally charged on the amount actually utilised rather than the entire sanctioned limit, depending on the terms of the facility.
A term loan, on the other hand, involves receiving a lump sum from the lender and repaying it through scheduled instalments over an agreed tenure. The repayment structure may include monthly EMIs covering both principal and interest. Since the loan amount and repayment schedule are established upfront, borrowers can plan their monthly finances more easily. Term loans are commonly considered for planned expenses such as business expansion, purchasing equipment, education, home improvement, or other significant financial requirements where the borrower knows the approximate amount needed.
2] Difference between Overdraft and Loan:
The key difference between an overdraft facility vs term loan is flexibility. An overdraft allows the borrower to draw and repay funds within the approved limit, subject to the lender’s conditions. As money is repaid, the available borrowing limit may become available again. A term loan generally follows a fixed repayment schedule and does not provide the same revolving access to funds.
Interest costs are another important consideration. With an overdraft facility, interest may be linked to the amount utilised and the duration for which the funds remain outstanding. This can be beneficial when withdrawals are limited or short-lived. However, overdraft facilities may involve renewal charges, processing fees, or other conditions.
3] Repayment Possibility:
The choice also depends on repayment certainty. A term loan can be appropriate when income or business cash flow is stable enough to support regular EMIs. An overdraft may be more suitable when cash inflows and outflows vary, and the borrower wants access to funds only when necessary. However, the flexibility of an overdraft should not encourage unnecessary borrowing, as prolonged utilisation can increase the overall interest burden.
Before choosing between an overdraft facility and a term loan, borrowers should assess the purpose of borrowing, required amount, expected repayment period, cash-flow pattern, interest rate, processing fees, renewal requirements, collateral requirements, and prepayment conditions. It is also important to check the lender’s eligibility criteria and understand whether the facility is secured or unsecured.
Conclusion
Ultimately, there is no universally better option between an overdraft and a loan. An overdraft can be useful for flexible and short-term funding needs, whereas a term loan can work better for larger, planned expenses requiring structured repayment. Comparing the total cost of borrowing and matching the repayment structure with actual financial needs can help borrowers make a more informed borrowing decision.